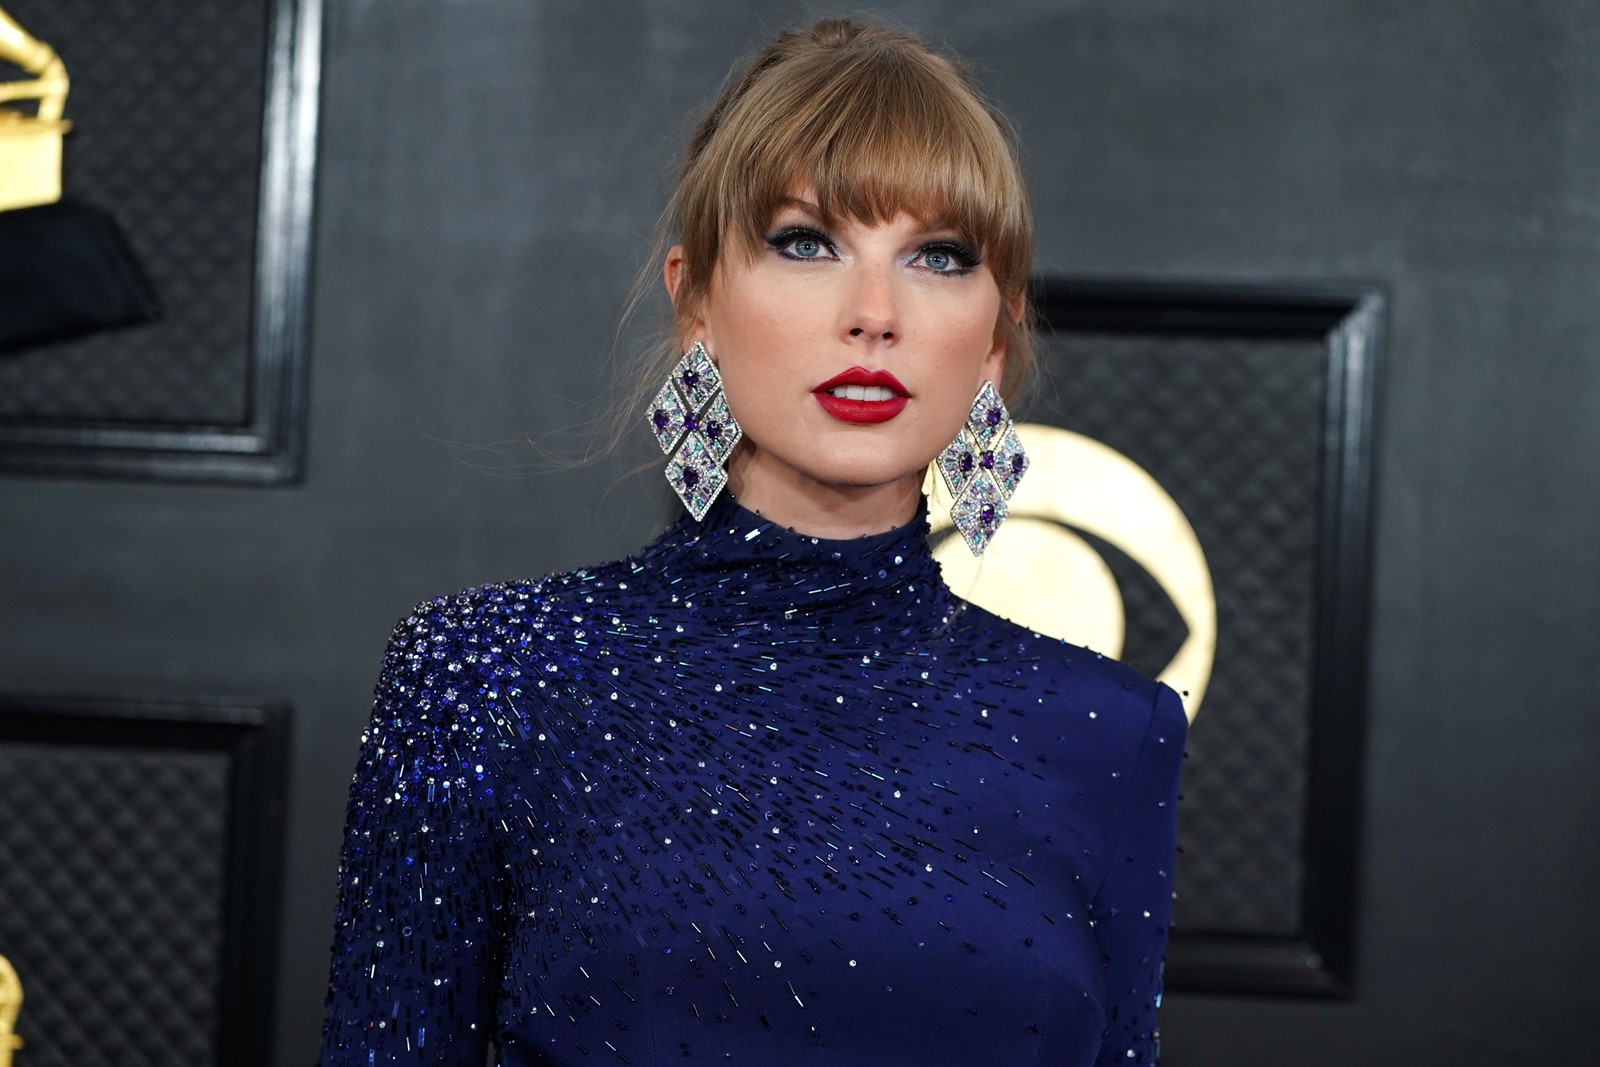


Taylor Swift wasn’t the one who backed out of a partnership with cryptocurrency exchange FTX before the company went bankrupt, despite claims to the contrary.
In December, reports emerged that the “Anti-Hero” singer, 33, was the reason the deal fell through after six months of negotiations. The deal reportedly would have been valued at around $100 million.
Earlier this year, Adam Moskowitz — the class-action lawyer who alleged in a lawsuit that FTX promoters such as Tom Brady and Shaquille O’Neal were among those who misled investors — publicly praised Swift for being “the one person” to do her due diligence. He claimed she asked FTX to provide evidence that their business was legitimate, and the partnership fell through after that.
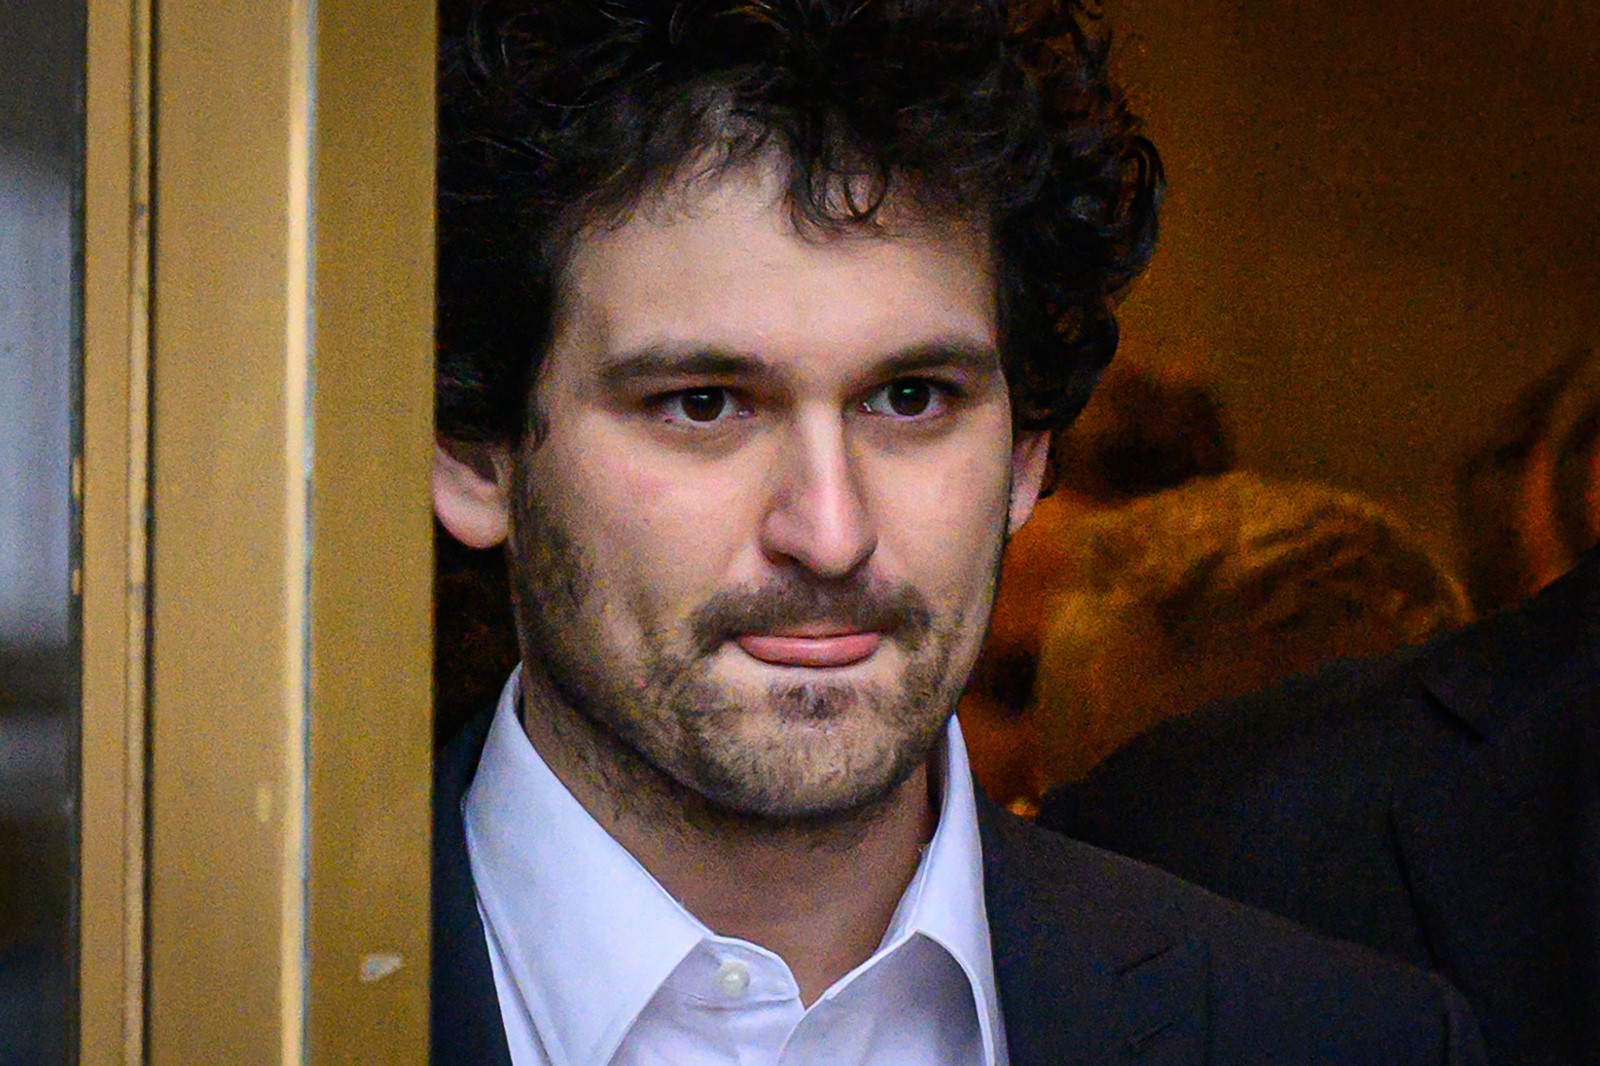
But on Thursday, an insider with knowledge of the situation told CNBC that Swift was fully on board and even had sent a signed agreement before FTX higher-ups swayed founder and CEO Sam Bankman-Fried to step away from the deal for reasons unreported. Multiple sources told The New York Times the same account, and Moskowitz admitted he had no inside information about the discussions between FTX and Swift.
Not only did FTX go bankrupt in November — just weeks before The Financial Times first reported on the deal that never quite got off the ground — but multiple executives since have been criminally charged.
Bankman-Fried, 31, was arrested in the Bahamas late last year and subsequently extradited. He is facing over a dozen charges, among them wire fraud and money laundering.
The case against the embattled entrepreneur and former billionaire, who has pleaded not guilty to all the charges against him, will be split into two separate Manhattan trials, a judge decided last month.
The first of these trials will begin in October.
 PREVIOUS ARTICLE