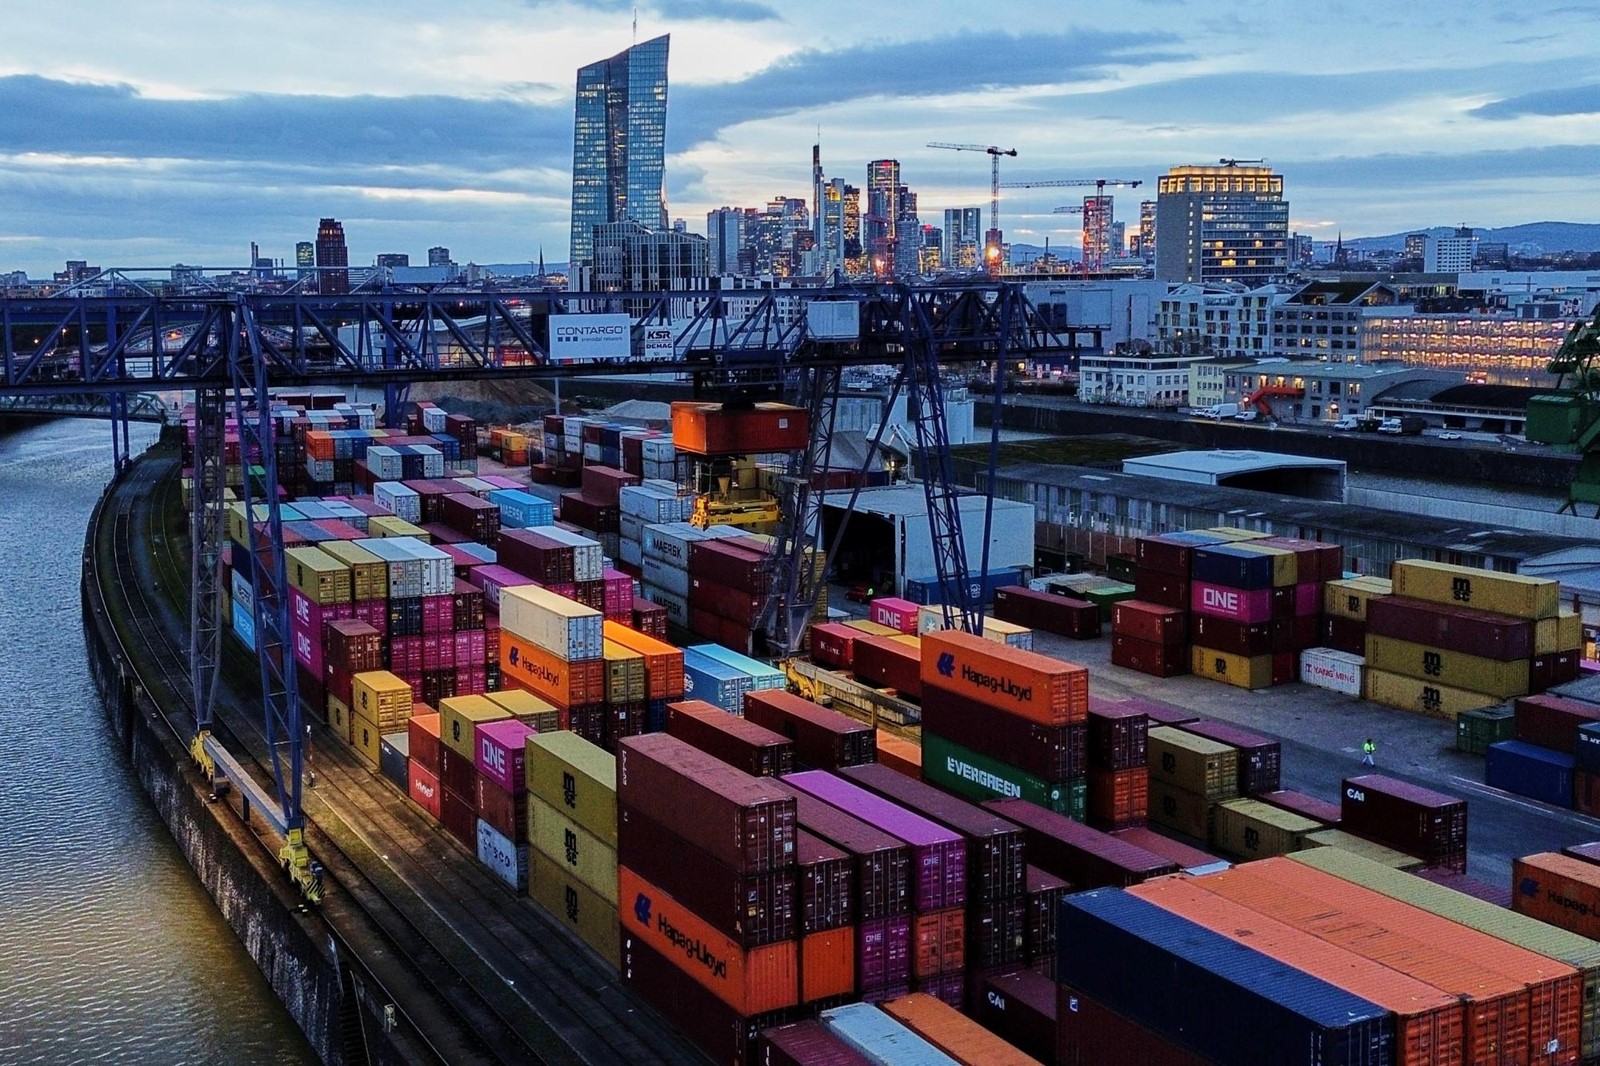


Some two dozen states challenged President Donald Trump’s new global tariffs on Thursday, filing a lawsuit over import taxes he imposed after a stinging loss at the Supreme Court.
The Democratic attorneys general and governors in the lawsuit argue that Trump is overstepping his power with planned 15% tariffs on much of the world.
Trump has said the tariffs are essential to reduce America’s longstanding trade deficits. He imposed duties under Section 122 of the Trade Act of 1974 after the Supreme Court struck down tariffs he imposed last year under an emergency powers law.
Section 122, which has never been invoked, allows the president to impose tariffs of up to 15%. They are limited to five months unless extended by Congress.
The lawsuit is led by attorneys general from Oregon, Arizona, California and New York.
“The focus right now should be on paying people back, not doubling down on illegal tariffs,” said Oregon Attorney General Dan Rayfield. The suit comes a day after a judge ruled t hat companies who paid tariffs under Trump’s old framework should get refunds.
The White House said Trump is acting within his power.
In a cash crunch, Oracle slashes jobs
Oracle is planning to ax thousands of jobs, among its moves to handle a cash crunch from a massive AI data center expansion effort.
The job reductions will affect divisions across the company and may be implemented as soon as this month, according to people familiar with the matter who asked not to be named discussing the still-private plans. Some of the cuts will be aimed at job categories that the company expects it will need less of due to AI, two of the people said.
Led by Chairman Larry Ellison, Oracle is embarking on a historic build-out of data centers to power AI workloads for customers such as OpenAI.
The reductions being planned are expected to be wider-reaching than the company’s typical rolling job cuts, according to the people. This week, Oracle announced internally that it would be reviewing many of the open job listings in its cloud division, effectively slowing down or freezing the hiring process, according to people with knowledge of the move.
Oracle declined to comment. The company had about 162,000 employees globally as of the end of May 2025. Planning for the workforce reductions is still active and could change, the people said.
Morgan Stanley trimming workforce
Morgan Stanley is laying off roughly 2,500 employees as job cuts continue this year in the financial sector.
The layoffs at Morgan Stanley, which account for roughly 3% of its workforce, are taking place across the entirety of investment bank, a person with knowledge familiar with the matter told The Associated Press on the condition of anonymity as the firm is not making a public statement about the layoffs.
Like other firms, Morgan Stanley aggressively hired during the pandemic, going from 60,000 employees in 2019 to 82,000 employees by year end 2022.
The company had 83,000 employees at the end of 2025. Tens of thousands of job cuts have already been made just two months into the new year, many of them white collar.
The financial sector has not been immune. Citigroup and Blackrock have reportedly trimmed back their headcounts, and last week, financial technology company Block, which owns Cash App and the point-of-sale company Square, announced it would lay off 40% of its workforce. While Block founder Jack Dorsey cited productivity gains in AI as the reason for the layoffs.
Berkshire Hathaway relaunches buy-backs
Berkshire Hathaway is buying back shares for the first time in nearly two years, and new CEO Greg Abel said he has no immediate plans to sell off Kraft Heinz shares now that the packaged food giant has shelved its plan to split the company into two.
Abel appeared on CNBC Thursday — less than a week after releasing his first letter to shareholders after taking over the top job at Berkshire from legendary investor Warren Buffett in January.
Berkshire also took the unusual step of filing a formal notice with the Securities and Exchange Commission that it had begun repurchasing its shares Wednesday for the first time since May 2024.
When Kraft first announced its plan to split the company in two last fall, Abel and Buffett expressed concerns about that because of the costs involved and the current struggles for some of the brands. So Abel said he agreed with new Kraft CEO Steve Cahillane’s decision to pause the split.
“For Steve to come in and say we’re pausing it, there’s opportunities within Kraft Heinz to fix things and get the business back on track and then he’ll evaluate things. We thought that was absolutely the right approach,” Abel said.
Compiled from Associated Press and Bloomberg reports.
 PREVIOUS ARTICLE