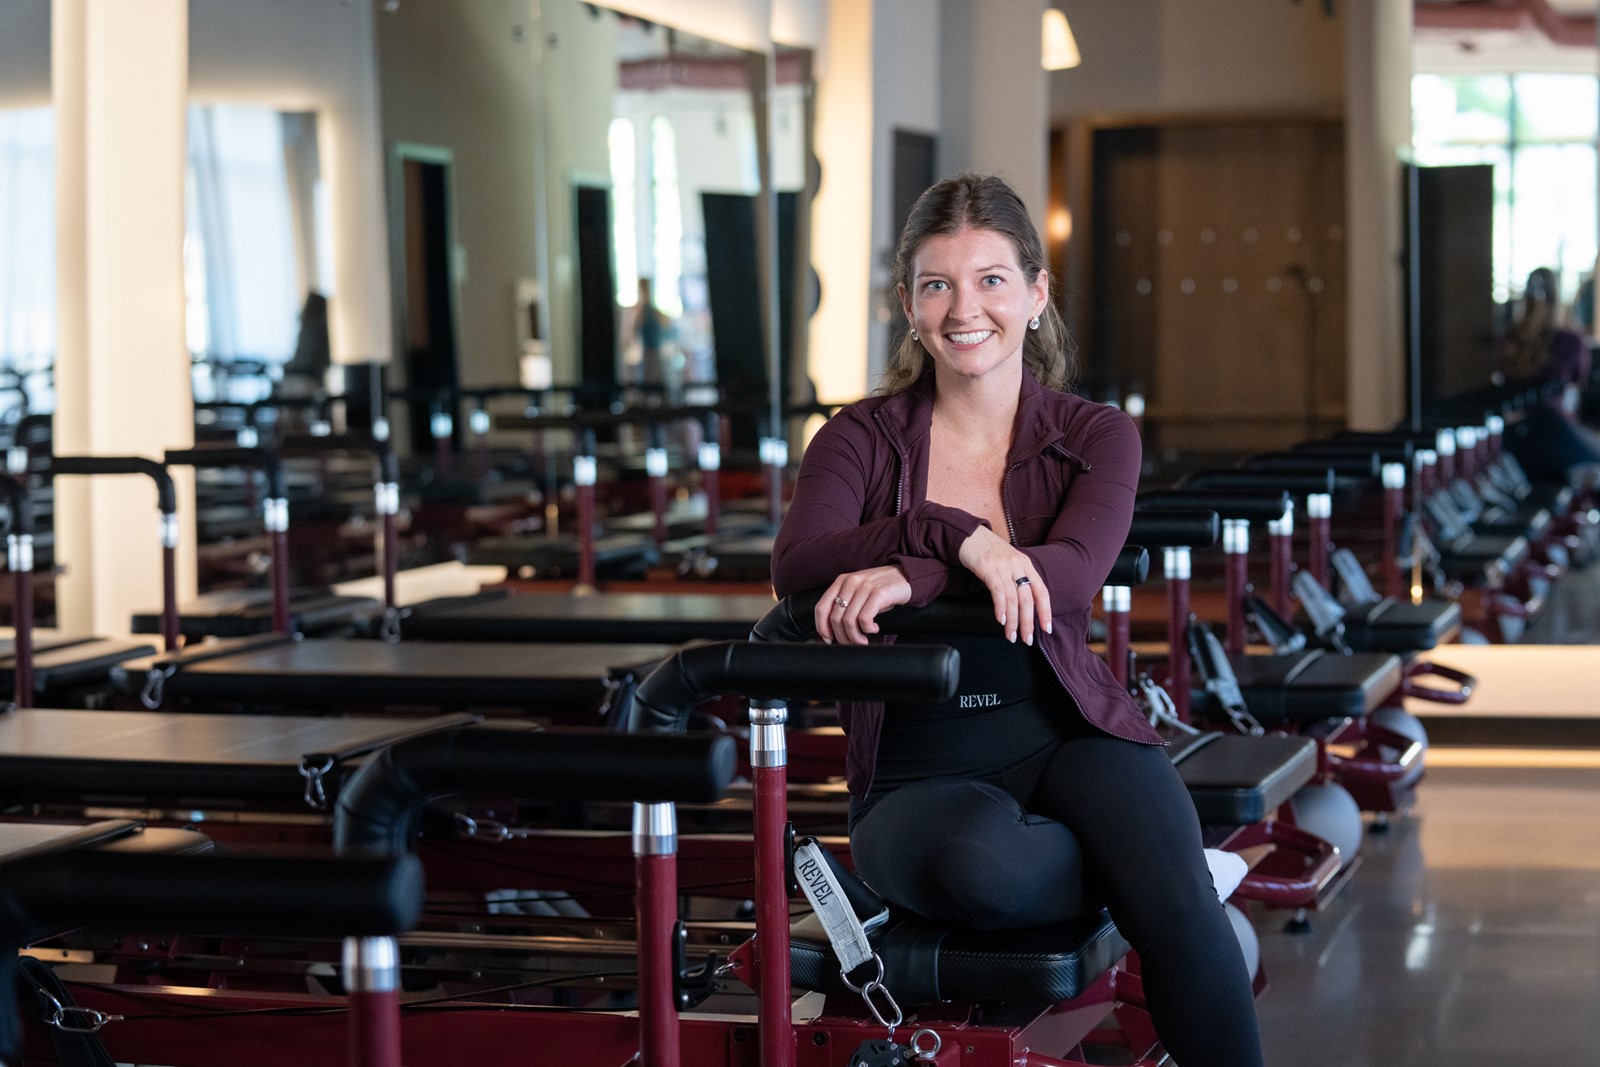


Cassidy Winkler was working as a flight attendant on private jets when inspiration struck.
It was the offseason for the professional hockey players she helped ferry around, and things at her job were slow. Eager for a diversion and missing the Pilates she had come to love as a college student, she went searching for studios near her home in Madison, Wis., but couldn’t find any.
“That’s when I came up with the idea,” she said.
She started researching how to start her own boutique Pilates business, including what kind of training instructors would need. By early 2025 — and with assistance from chatbots including ChatGPT — she had come up with a name, Revel Method Pilates, a logo and a plan.
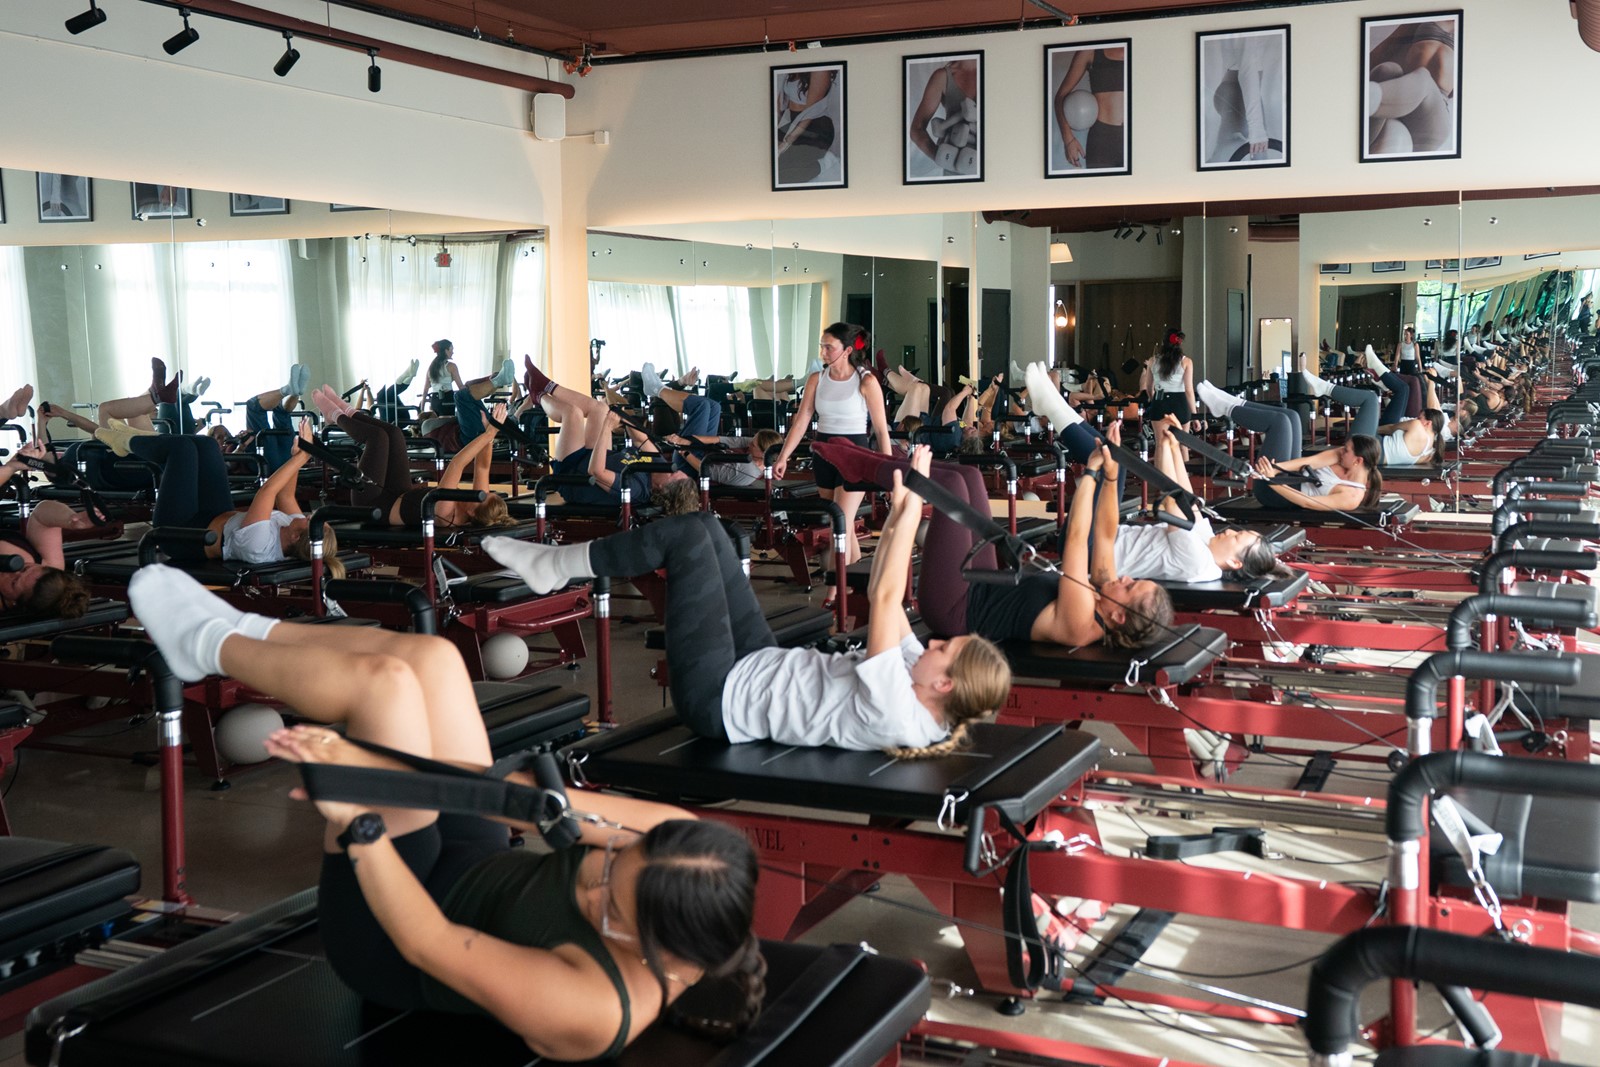
Soon, Winkler, 26, had opened studios in Lake Geneva, Madison and Monona. She now has 65 employees and is set to unveil a fourth studio this year.
Across the country, founders like Winkler are powering an entrepreneurial renaissance.
Jump-started by the pandemic, when a confluence of factors including mass layoffs and remote work led to a flood of business creation, and supercharged by the rise of artificial intelligence, startup activity is booming after a decades-long slump.
Americans filed 5.7 million applications last year to start new businesses, according to the Census Bureau, the most in the two decades the government has kept track. New business applications through the first half of this year continued to climb. The strong run of business creation is one of the most surprising and welcome economic developments of the postpandemic era. New businesses help drive innovation and productivity growth. Although many fail or remain small, some could develop into giants that spur job growth for years to come.
“The sustained high rate of both Main Street and growth-oriented entrepreneurship over the past five years is a piece of super good news about the future of the economy,” said Scott Stern, an economist at the Massachusetts Institute of Technology.
Data on the number of businesses formed each year lags, so it will take time to determine whether the increase in new business applications translates to a rise in real-world businesses and hiring. In 2023, the most recent year for which the data is available, 500,000 businesses formed, according to the Census Bureau. That was down slightly from the previous year but broadly consistent with an upward trend.
Economists offer a range of factors that could explain the surge in entrepreneurship. First, layoffs during the pandemic left millions of Americans without traditional work and pushed some people to start businesses of their own. Generous government stimulus benefits and low interest rates lessened the financial burden. The pandemic may also have led to a realignment of priorities that made would-be entrepreneurs more willing to pursue long-harbored fantasies.
More recently, there are signals that AI is adding fuel.
A recent paper from economists at the University of British Columbia and the Stockholm School of Economics found that generative AI was “spurring entrepreneurial activity” in the United States, both by giving rise to new ventures built around the technology and by making it cheaper to start enterprises.
“AI tools can do very many different things very well,” said Jan Bena, an associate professor at the University of British Columbia and one of the study’s authors. “That’s the reason why you see so much entry.”
According to a recent report from Gusto, a small-business payroll and benefits service, nearly 60% of founders on its platform who started businesses last year said they used AI, and half said the technology made it cheaper and faster.
The technology appears to be greasing the path for entrepreneurs, removing some barriers and allowing them to get their enterprises off the ground more quickly. Chatbots are effectively serving as virtual collaborators that can answer questions, carry out tasks and write code.
Winkler, the founder of Revel Method Pilates, said she used AI to refine her communications with clients, conduct research and develop marketing. She often turns to chatbots for advice when she isn’t feeling confident about a new concept and considers AI an indispensable thought partner.
“I don’t know how people did business prior to AI some days,” she said.
Census data shows that the rise in business applications has been driven by startups that are not likely to hire workers rather than by those that are. That, some economists believe, is more evidence that AI is eviscerating obstacles to entrepreneurship.
Ernie Tedeschi, chief economist at Stripe, a financial tech firm, said the government’s data, as well as an analysis of Stripe users, indicated a jump in solo entrepreneurs who might be using AI for tasks that once required human employees.
“We think that AI is actually assisting people with starting their own business,” he said.
AI also seems to be propelling a rush of new businesses related to the technology itself. A paper that studied filings from 2004 to 2023 found that AI-related business applications grew rapidly toward the end of that period.
And business applications since the beginning of 2025 have soared in sectors that are heavily exposed to AI, including information and professional, scientific and technical services.
“Startups are drawn to innovation,” said John Haltiwanger, a University of Maryland economist and an expert in business formation and economic dynamism. “I do think this is related to a technological wave.”
That was the case for Arjun Lalwani and Helly Shah, who started an automated mortgage broker called Ralo last year.
In their previous jobs at Google, both Lalwani, 28, and Shah, 27, saw firsthand the capabilities of AI models. Both were also frustrated with their experiences obtaining mortgages.
That combination inspired them to build a company that used AI tools to make getting a mortgage less onerous and costly, they said. They spoke to hundreds of homebuyers, got licensed as mortgage loan officers and joined Y Combinator, a startup incubator.
“We were like, ‘Wow, there’s so many tricks here, and we should be using all this cool AI tech we’re building at Google and applying it to this part of the economy,’” Lalwani said. “That was kind of the inkling of the idea.”
AI also helped them set up the company, they said. Rather than hire a team of engineers to write the company’s code, they created it on their own. They started originating loans in March and are chasing their first 100 customers. They said in June that Ralo had raised $2.9 million in venture capital.
Other factors could be stoking the rise in startup activity.
The low-hire, low-fire labor market that has persisted for much of the past two years could be causing some unemployed workers to turn to other sources of income. The high-flying stock market and lofty home prices could be encouraging business investments. E-commerce platforms such as TikTok Shop could be producing a new category of third-party sellers. Swelling business creation could be a reflection of optimism in the country’s trajectory. It is also possible that AI is making it easier to fill out applications.
 PREVIOUS ARTICLE