

The government should “forcefully seek” binding commitments from foreign buyers of British tech and life sciences start-ups to maintain a share of jobs and research in the UK, according to a new paper published by Cambridge University’s Judge Business School.
The paper argues for more focus on maintaining the UK’s productive capacity rather than trying to ensure that start-ups remain British. “Foreign acquisition is not the problem — and neither is foreign ownership,” it said.
It comes after early-stage British tech and life sciences companies were acquired by foreign buyers, including Oxford University spin-outs Oxford IonQ and Organ Ox as well as the Cambridge biotech company Abcam.
The paper found that 40 UK deeptech companies were acquired on average each year between 2015 and 2025. If half of these had negotiated a “binding commitment” that resulted in the creation of 25 new UK-based jobs over five years, it would generate £2.5bn in gross value added over a decade.
The paper pointed to SoftBank’s commitment to keep Arm’s headquarters in Cambridge after it acquired the semiconductor designer in 2016. It also committed to at least double Arm’s UK headcount in five years.
Many in the sector also point to DeepMind’s decision to stay in London after its acquisition by Google in 2014.
DeepMind alumni have founded or been part of the founding team at some of the UK’s most promising tech companies including Ineffable Intelligence, Isomorphic Labs, Recursive Superintelligence and ElevenLabs.
“The UK — government, universities, founders and the investment community together — should seek commitments from international investors and acquirers to create jobs and maintain a meaningful UK footprint for companies born in the UK, nourished by UK taxpayer investment, and first taking root in UK soil,” the paper said. “The fruits from the UK’s innovation orchard can be harvested — ownership can change, returns can flow abroad — without pulling up the tree.”
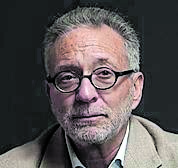
The paper was written by Pascal Levensohn, chair of the global advisory board for the Cambridge Innovation Hub, which seeks to transform the UK’s capacity to scale world-leading deep tech and life sciences companies.
Ensuring that more high-growth tech and life sciences companies remain in the UK has been a government priority. It has pushed for pension funds to invest at home and also reformed the rules to encourage listing in London.
While the government has ruled out introducing an exit tax on university spin-outs that move their operations abroad, officials may still tighten conditions on public grants to ensure that intellectual property remains in the UK.
Sir Ian Chapman, the chief executive of UK Research and Innovation (UKRI), a national funding agency, said “the UKRI terms and conditions on IP are the most liberal of any research investor in any of the G7 countries ... we are having a look at that again. We are consulting and asking for input on whether those terms are right.”
Roughly 4 per cent of spin-outs from UK universities have moved abroad in recent years, according to a Centre for Cities report last year. Levensohn’s paper acknowledged that since most transactions are private, it is much more difficult to enforce binding commitments than for public companies.
However, it argued that the instruments to secure these commitments already existed, including contractual covenants in share purchases, conditions on public fundings and “reputational mechanisms” that reward investors who honour their commitments.
UK start-ups have attracted $23.4bn in investment this year, just over a third of the European total and on track for a record annual total. But companies still find it difficult to access domestic capital to scale. In the first half of the year, only 16 per cent of capital in funding rounds over $250m came from the UK.
A government spokesperson said: “We are making Britain one of the best places in the world to start, scale and grow a business, and secured more than £3bn in investment in the first year of our life sciences sector plan.”